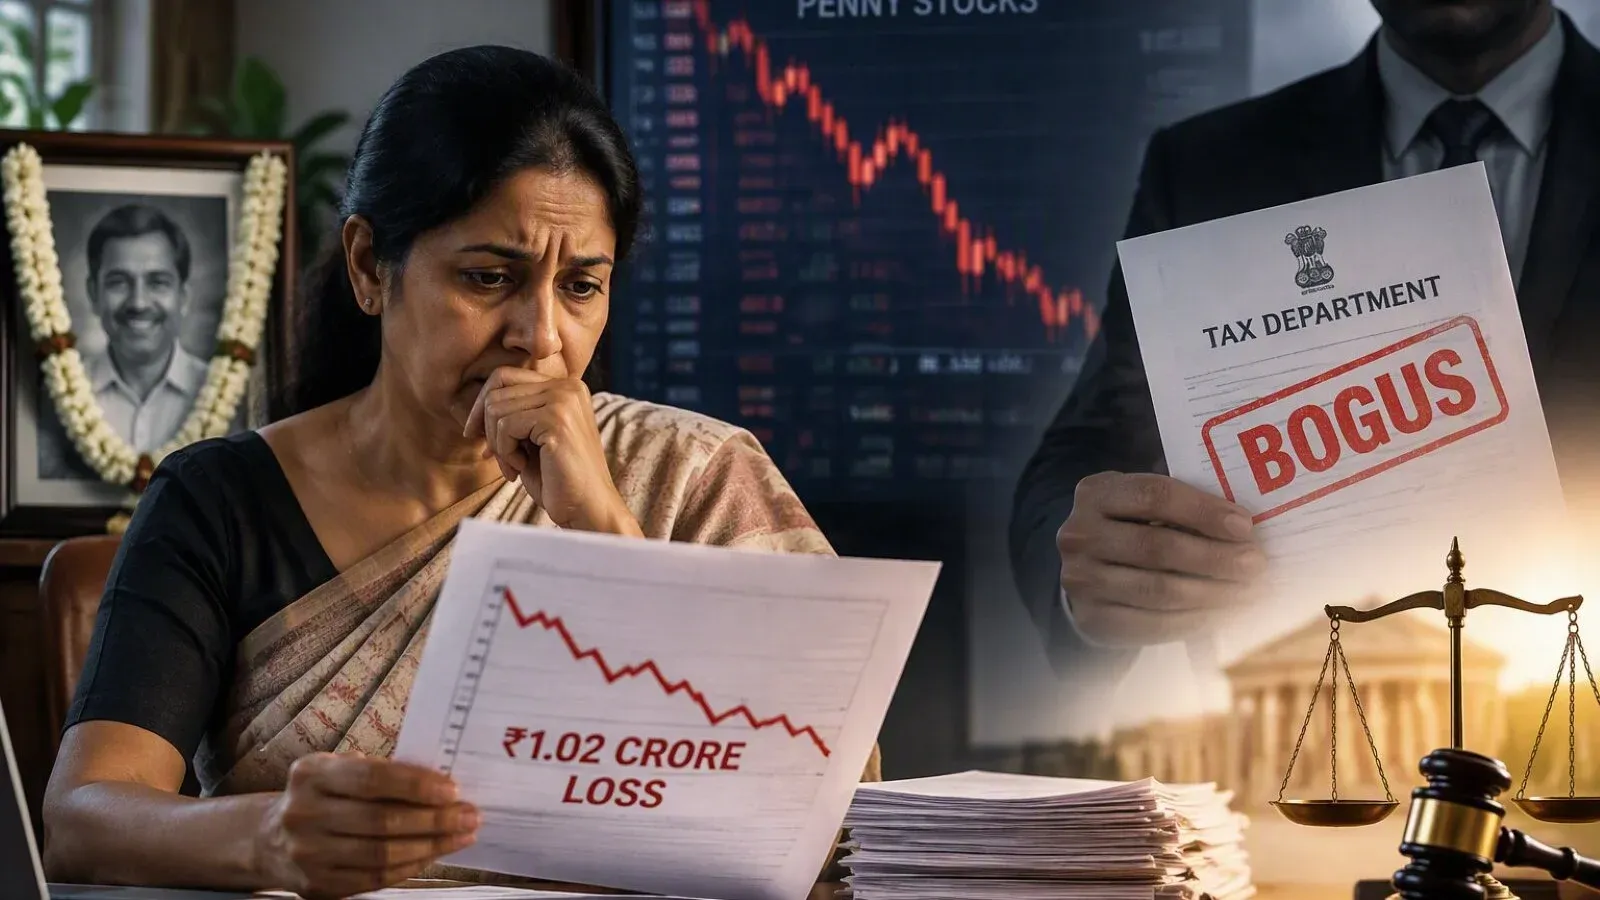
When Usha Jain sold penny stocks inherited from her late husband at a loss of over ₹1 crore, the tax department challenged the transaction as bogus. However, the Delhi Income Tax Appellate Tribunal (ITAT) ruled in her favor, clarifying how inherited shares should be treated for tax purposes. This ruling provides important guidance for families inheriting shares, especially when penny stock trades are questioned.
- Heirs are treated as the previous owners of inherited shares, not as manipulators.
- A sale resulting in a loss cannot be reclassified as concealed income without full investigation.
- Proper documentation like broker notes and bank statements is crucial for tax relief.
- Capital losses must be claimed in the correct tax return to be allowed.
What happened in the case of Usha Jain?
D.K. Jain bought shares of SVC Resources Limited during 2011-12 and 2012-13 as a regular investment. After his death in March 2014, his wife Usha inherited these shares. She sold part of the holding at a significant loss and filed income tax returns as his legal heir, declaring the loss from the sale.
However, the tax department rejected the late husband's return as "non-est" (non-existent) and treated the sale as Usha's own transaction. They classified the shares as bogus penny stocks and added the sale proceeds of ₹24,33,546 as unexplained income, along with additional amounts, leading to a total tax addition of ₹28,21,913.
Why did the tax department challenge the sale?
The reassessment was triggered because the shares sold were penny stocks, and the department suspected bogus long-term capital gains manipulation. The assessing officer relied on an investigation report and did not accept the loss claimed by Usha Jain.
How did the ITAT respond to these allegations?
The ITAT found the tax officer's approach flawed. It noted that Usha Jain had not made any gains but had incurred a long-term capital loss of about ₹1.02 crore. The tribunal emphasized that the officer should have examined the entire transaction rather than relying solely on the investigation report.
The tribunal also pointed out that there was no evidence linking Usha Jain to any dubious transactions such as price rigging or exit providers. It referred to previous court rulings that shares bought and sold through registered brokers and stock exchanges, with payments through banking channels and securities transaction tax paid, cannot be treated as bogus penny stocks.
What does this ruling mean for heirs of penny stocks?
The ruling clarifies that heirs who inherit shares should be considered the previous owners for tax purposes. If they sell the shares at a loss, that loss is genuine and should not be treated as concealed income. Proper documentation like contract notes, demat statements, and bank records can support the legitimacy of the transaction.
However, the tribunal also noted that the capital loss must be claimed in the correct tax return. Since Usha Jain claimed the loss in the return filed on behalf of her deceased husband and not in her own return, the tribunal did not allow the loss to be carried forward in her name.
What are the key takeaways from the ITAT ruling?
- A sale producing a loss cannot be recast as concealed income without a thorough investigation.
- Heirs are treated as the previous owners, not as manipulators of inherited shares.
- Documentation of original purchase and sale transactions is essential for tax relief.
- Capital losses must be claimed in the appropriate tax return to be recognized.
This ruling is significant for families inheriting shares, especially penny stocks, and provides a clear legal precedent on how such transactions should be treated by tax authorities.