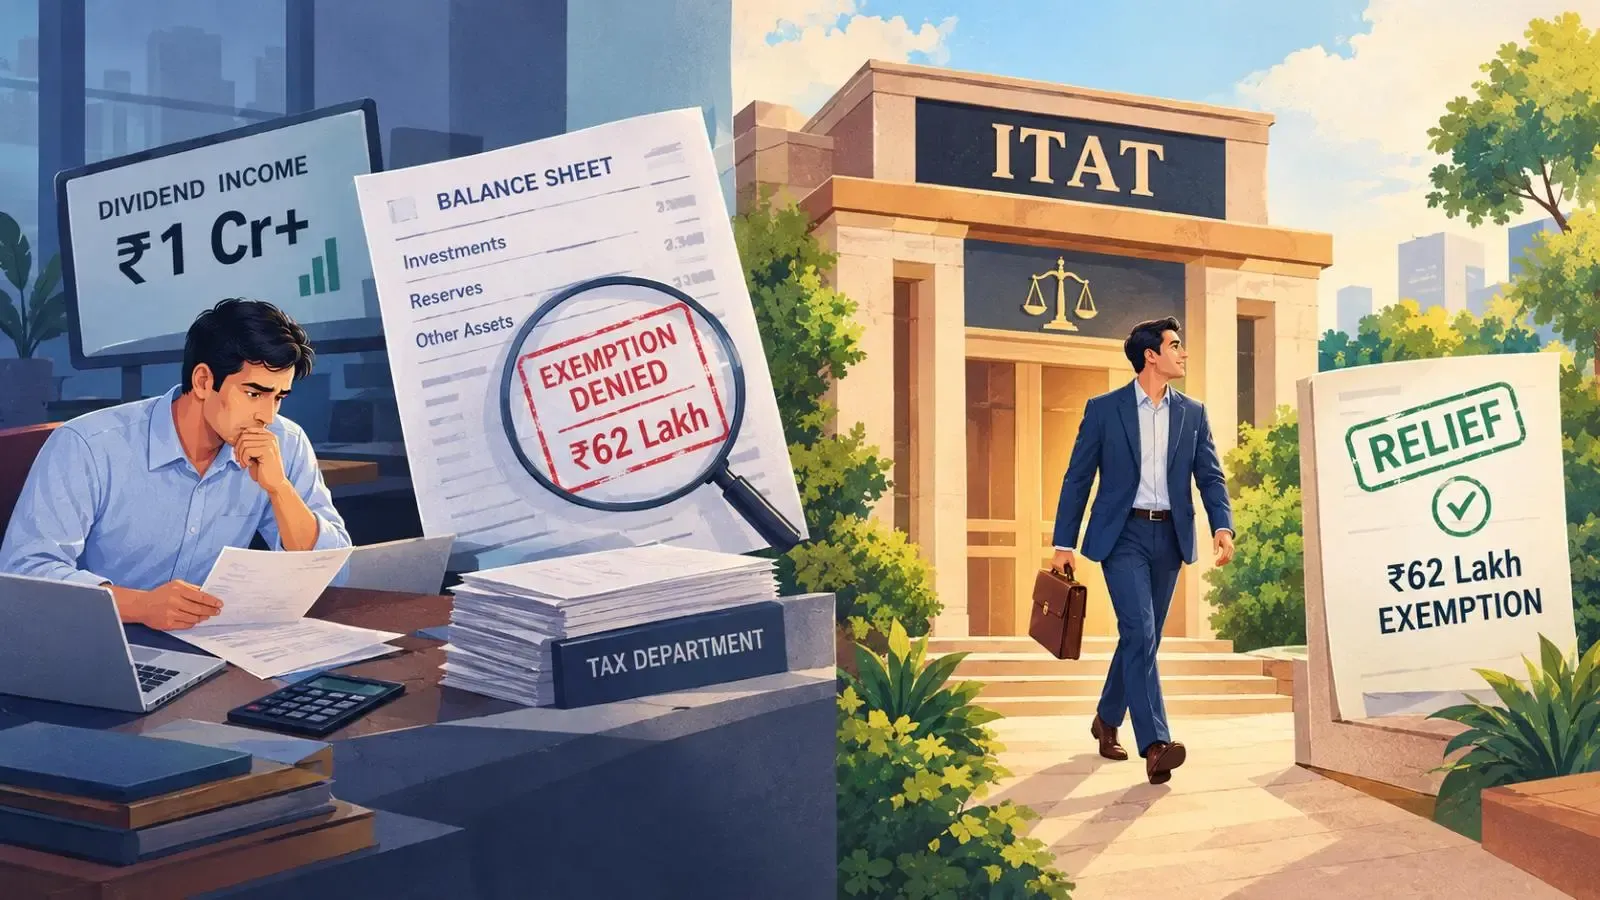
What happens when a tax officer misunderstands company balance sheet figures and denies a dividend tax exemption? The Income Tax Appellate Tribunal (ITAT) recently ruled on such a case involving a shareholder who received over ₹1 crore in dividends but was initially denied a ₹62 lakh exemption. This ruling is important for equity investors who claimed dividend exemptions before 2020 and now face tax scrutiny.
- The shareholder received ₹1,02,83,600 in dividends from Galaxy Surfactants Limited.
- The tax officer incorrectly used the next year's proposed dividend figure to deny ₹62,16,690 of exemption.
- The ITAT accepted the correct dividend figure from the previous year and allowed the exemption.
- This case shows the importance of submitting proper financial documents and resolutions during tax assessments.
- Dividend income was exempt under section 10(34) of the Income-tax Act before 2020.
What was the background of the tax dispute?
Unnathan Shekhar, an individual shareholder, held 41,13,440 equity shares in Galaxy Surfactants Limited, representing 11.60% of the company's paid-up equity. He received a dividend of ₹1,02,83,600 for the assessment year (AY) 2013-14 and claimed it as exempt under section 10(34) of the Income-tax Act. However, the assessing officer (AO) denied exemption of ₹62,16,690, suspecting an excess claim.
How did the tax officer arrive at the denial?
The AO examined the company’s balance sheet as of March 31, 2013, and noted a proposed dividend of ₹3,55,00,000. Applying the shareholder’s 11.60% stake, the AO calculated the dividend as ₹41,13,440, which was much lower than the claimed exempt amount. The AO concluded that the shareholder had claimed excess exemption and rejected ₹62,16,690 of it.
What evidence did the shareholder provide?
Shekhar’s counsel submitted the company’s financial statements for the years ending March 31, 2012, and March 31, 2013, along with certified copies of resolutions passed at the Annual General Meetings (AGMs). These documents showed that the proposed dividend of ₹3,55,00,000 in the March 31, 2013 balance sheet was for distribution in the next financial year (FY 2013-14), not the current assessment year.
Which dividend figure was relevant for AY 2013-14?
The dividend relevant to AY 2013-14 was the one for the year ended March 31, 2012. The company had proposed a dividend of ₹8,86,36,800 at ₹2.50 per share, approved by shareholders on August 3, 2012. Shekhar received this dividend on August 14, 2012, which matched the exempt amount he claimed.
What did the ITAT conclude?
The ITAT found that the AO had misunderstood the balance sheet figures and mistakenly used the proposed dividend for the next financial year instead of the actual dividend received. The tribunal noted that the correct dividend figure was visible on the same page of the financial statements. It directed the AO to allow the full exemption of ₹1,02,83,600 and set aside the disallowance of ₹62,16,690.
What lessons can equity investors learn from this case?
This ruling highlights the importance of carefully submitting complete financial documents and resolutions when claiming dividend exemptions. It also shows how a simple confusion between two years’ dividend figures can lead to tax disputes. Investors who claimed exemptions before 2020, when dividend income was exempt under section 10(34), should ensure their claims are supported by proper evidence to avoid scrutiny.