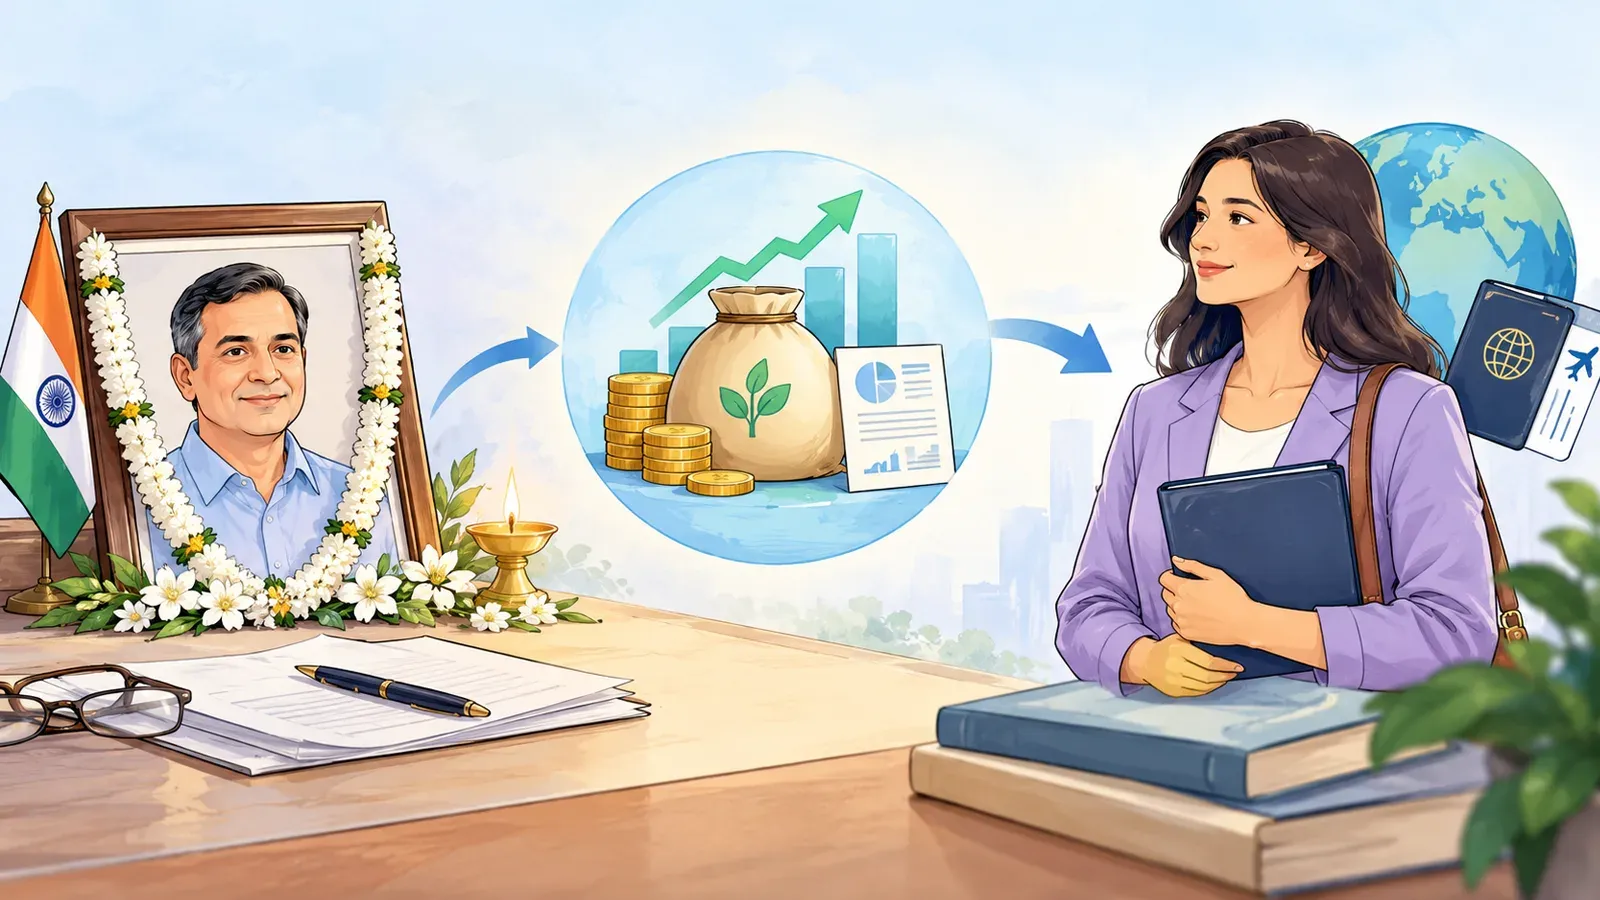
What happens to Indian mutual fund investments after the death of an investor if the nominees are US citizens with Overseas Citizen of India (OCI) cards? This question is important for many Indian investors whose family members live abroad, especially in the United States. The process involves specific steps related to bank accounts, documentation, and taxation, which we explain here.
- Nominees with OCI cards can open Non-Resident Ordinary (NRO) accounts remotely in India.
- Basic documents required include US Passport, OCI card, US proof of address, and Indian PAN card (if available).
- New folios can be created with transmitted investments, allowing nominees to redeem mutual funds.
- Tax will be deducted at source on redemption profits according to Indian tax laws for non-residents.
- Non-residents can remit up to 10 lakh USD annually from India with proper certification.
Can US Citizen Nominees Claim Indian Mutual Fund Investments?
Yes, nominees who are US citizens and hold OCI cards can claim mutual fund investments after the death of the original investor. They need to follow the transmission process, which involves creating a new folio in their name with the transmitted investments. This allows them to manage or redeem the mutual funds as per their wishes.
What Bank Account Is Required for Nominees Living Abroad?
Nominees living in the US can open an NRO account remotely with major Indian banks such as ICICI, HDFC, SBI, or Axis Bank. This account is necessary to receive proceeds from mutual fund redemptions. The account opening requires submitting documents like a US passport, OCI card, proof of US address, and an Indian PAN card if available. If the nominee does not have a PAN card, they can apply for one.
Are There Tax Implications for Non-Resident Nominees?
Yes, since the spouse and daughter are considered non-residents for income tax purposes, the mutual fund house will deduct tax at source on any profit earned from redemptions. The tax rates depend on the holding period and the type of mutual fund scheme. This ensures compliance with Indian tax laws for non-resident investors.
Do Nominees Need to Travel to India for the Process?
No, nominees do not need to travel to India to claim the investments. They can complete the account opening and transmission process remotely from the US by submitting the required documents. This makes the process convenient and accessible for investors’ families living abroad.
How Much Money Can Non-Residents Remit From India?
Non-resident nominees can remit up to 10 lakh USD every year from India. To do this, they must submit a certificate from a chartered accountant to the remitting bank. This allows them to transfer funds abroad legally and in compliance with Indian regulations.
In summary, Indian mutual fund investments can be smoothly transmitted to nominees who are US citizens with OCI cards. By opening an NRO account remotely and submitting the necessary documents, nominees can claim and redeem investments without traveling to India. Tax deductions will apply as per Indian laws, and repatriation of funds is possible within prescribed limits.