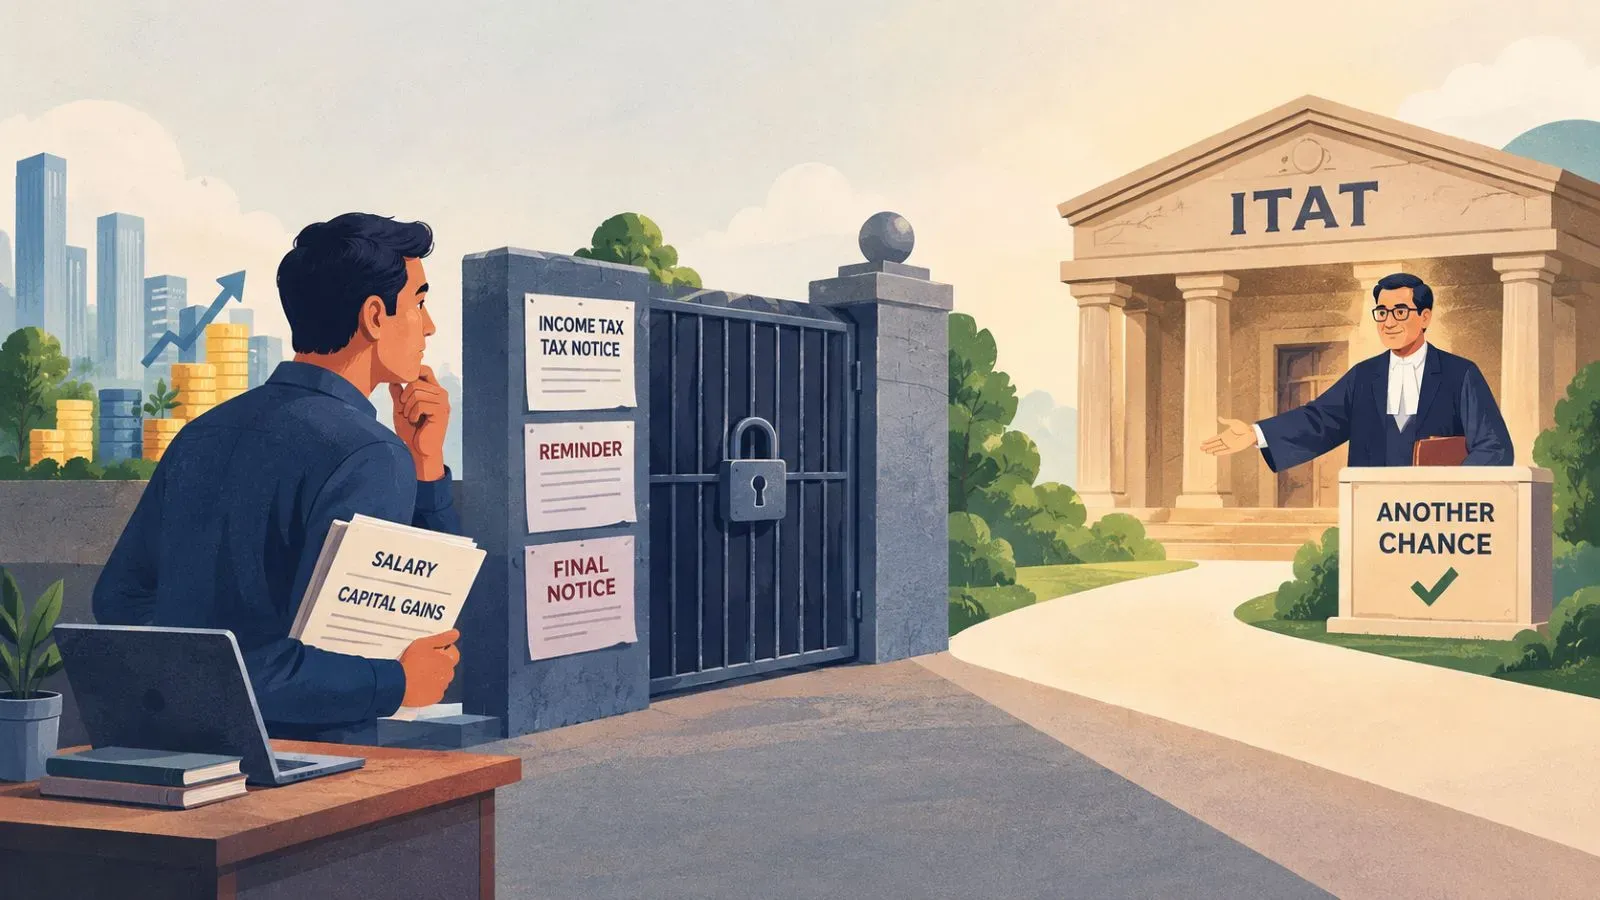
The Income Tax Appellate Tribunal (ITAT) recently gave a second chance to a taxpayer who earned salary and capital gains but failed to file his income tax return (ITR) on time and did not properly respond to tax notices. This ruling is important for taxpayers who miss deadlines and face assessments made in their absence.
- Taxpayer Mukesh Mishra did not file his ITR for assessment year 2020-21 despite earning salary and capital gains.
- The tax department issued notices under section 148 and section 142(1) but received limited responses.
- The assessing officer made large additions to his income, including unexplained investments and disallowed deductions.
- The first appellate authority dismissed his appeal without deciding on the merits because of non-participation.
- The ITAT restored the appeal for reconsideration, emphasizing the need for substantive justice.
- Taxpayers must actively engage in proceedings and keep contact details updated to avoid penalties.
What Happened in the Tax Case?
Mukesh Mishra, a resident of Thane, earned income from salary and capital gains during the assessment year 2020-21 but did not file his income tax return as required under section 139. The Income Tax Department found this through its Risk Management System and issued a notice under section 148 to reopen the assessment.
In response, Mishra filed his return on July 12, 2024, declaring a total income of ₹23,38,410. However, he largely failed to respond to further notices under section 142(1) and did not comply with a show cause notice.
What Additions Did the Tax Department Make?
Due to Mishra's lack of cooperation, the assessing officer completed the assessment based on available information and made several additions:
- Short-term capital gains of ₹11,71,078 calculated by adopting a low purchase value.
- ₹63,40,996 added under section 69 for securities purchased without actual delivery.
- ₹3,67,369 added under section 69 for securities purchased.
- ₹17,84,600 added under section 69 for immovable property.
- Disallowance of ₹2,00,000 claimed as housing loan interest deduction.
- Disallowance of ₹2,25,000 claimed under Chapter VI-A deductions (sections 80C, 80D, and 80CCD(1B)).
- ₹1,161 added to salary income for alleged short disclosure.
How Did the Appeal Process Unfold?
Mishra appealed against the assessment but failed to provide explanations, evidence, or written submissions. The Commissioner of Income Tax (Appeals) [CIT(A)] noted the absence of adjournment requests or submissions and issued notices to the email address on file.
After giving multiple opportunities, the CIT(A) dismissed the appeal ex parte, meaning without hearing Mishra and without deciding on the merits of the case.
Why Did the ITAT Give Another Chance?
Mishra's counsel argued before the ITAT that the dismissal violated natural justice because hearing notices were sent to an email address Mishra did not regularly check. He claimed his absence was not willful.
The ITAT acknowledged Mishra's failures but focused on the fact that the CIT(A) did not decide the appeal on its merits. To ensure substantive justice, the tribunal restored the appeal to the CIT(A) and directed that new hearing notices be sent to an email address provided by Mishra.
The ITAT also warned Mishra to take the proceedings seriously and submit all necessary evidence and written submissions to support his appeal.
What Are the Lessons for Taxpayers?
This case shows that ignoring tax return filing deadlines and tax notices can lead to severe financial consequences, including large additions to income and disallowed deductions.
However, if an appeal is dismissed without a decision on the merits, taxpayers may get another opportunity to present their case. To benefit from this, they must actively participate, keep their contact information updated, and provide proper evidence.
Taxpayers should avoid ignoring notices and ensure timely filing and responses to protect their rights and avoid penalties.