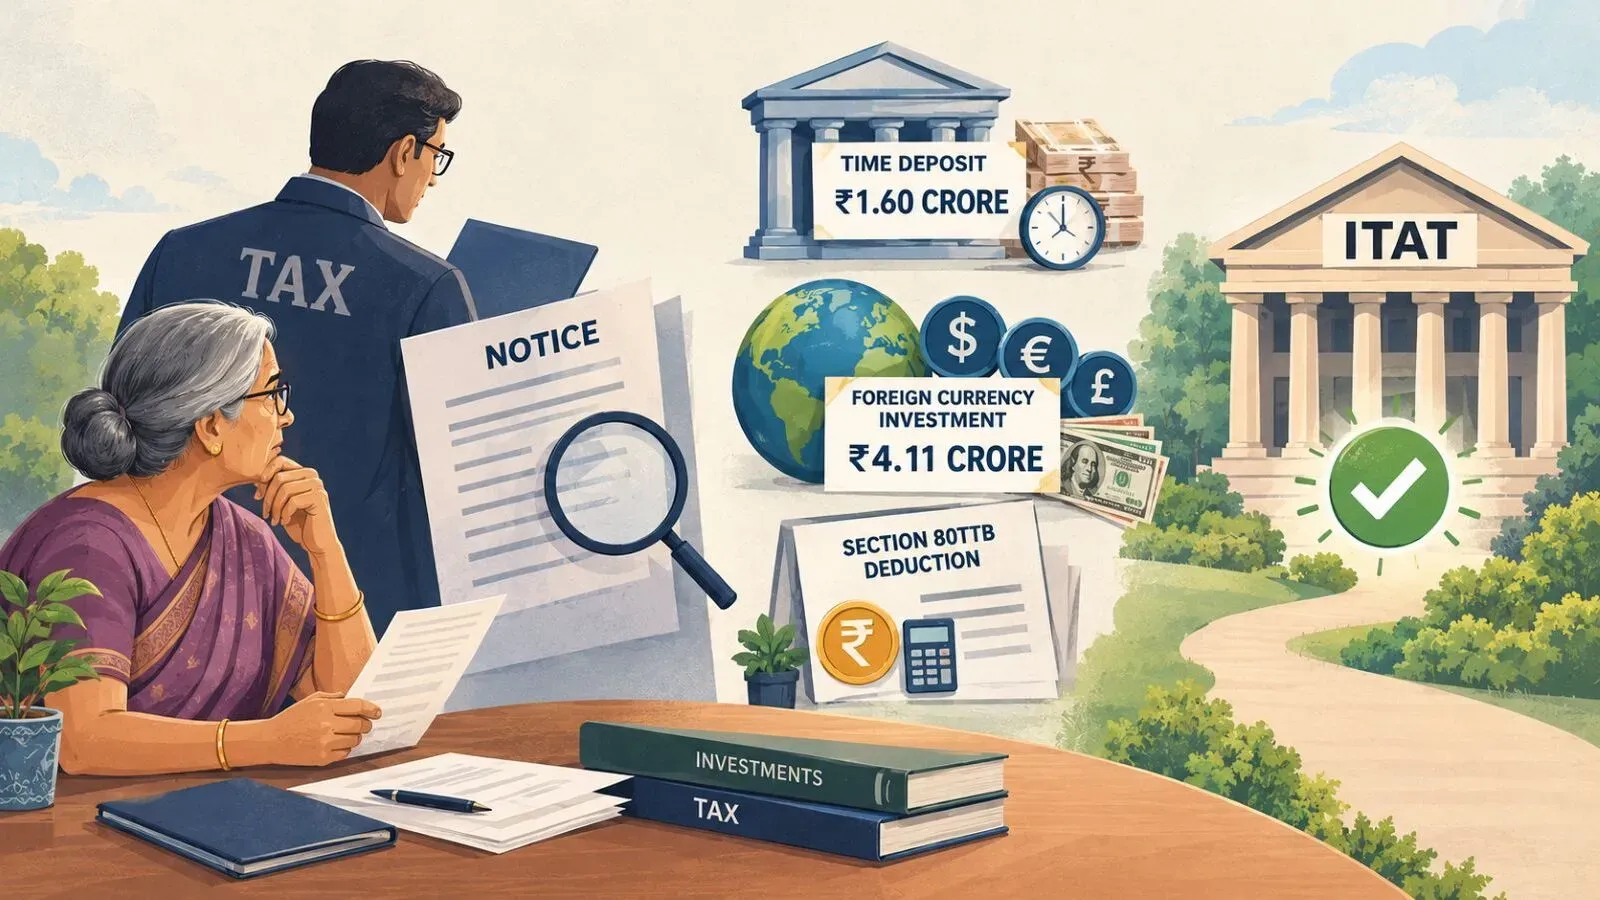
The Income Tax Appellate Tribunal (ITAT) recently addressed a case involving Mangala Joshi, a senior citizen living outside India, whose ₹1.60 crore time deposit and ₹4.11 crore foreign currency investments were questioned by the tax authorities. The tribunal’s ruling emphasizes that non-response to tax notices does not automatically mean the investments are unexplained, and taxpayers can seek a fresh hearing if they cooperate.
- Joshi declared ₹1.14 crore income but had ₹1.60 crore in time deposits and ₹4.11 crore in foreign currency investments.
- She claimed a ₹50,000 deduction under Section 80TTB for senior citizens.
- The tax department completed assessment without her response, adding the full amounts to her income.
- The ITAT allowed a fresh hearing, emphasizing the need for cooperation and updated contact details.
Why Did the Tax Department Question Joshi’s Investments?
Joshi filed her income tax return for the assessment year 2023-24 declaring a total income of ₹1,14,69,730. However, the tax department noticed large investments that did not match her declared income. These included ₹4.11 crore in foreign currency purchases and a ₹1.60 crore time deposit.
She also claimed a deduction of ₹50,000 under Chapter VI-A (Section 80TTB) for interest income earned by senior citizens. The tax authorities issued multiple notices for clarification, but Joshi did not respond, possibly due to her living abroad and other reasons beyond her control.
What Was the Outcome of the Initial Assessment?
Because Joshi did not reply to the notices, the assessing officer completed the assessment ex parte. The officer treated the ₹1.60 crore time deposit as unexplained investment and added ₹4.11 crore of foreign currency investments to her taxable income. The ₹50,000 deduction was disallowed, resulting in a total assessed income of ₹6.86 crore.
Joshi appealed to the Commissioner of Income Tax (Appeals), but again did not participate, leading to dismissal of her appeal.
How Did the ITAT Rule on This Case?
Joshi’s counsel informed the ITAT that she is a senior citizen residing outside India and that the investments were from the sale proceeds of a residential property sold in December 2020. She argued that these funds were already taxed in earlier years and that she could provide evidence if given a chance.
The ITAT noted her failure to respond earlier but allowed a fresh hearing. It did not decide whether the additions were correct but remitted the case back to the CIT(A) for reconsideration, emphasizing the importance of justice and fair opportunity.
The tribunal also set conditions: Joshi must cooperate with the tax department, update her contact details on the ITBA portal, and attend the hearing without seeking unnecessary adjournments.
What Are the Key Lessons for Taxpayers?
This ruling is important for senior citizens, non-resident taxpayers, and those living away from their registered addresses. It shows that:
- Ignoring tax notices can lead to large ex parte assessments.
- Non-response alone does not prove investments are unexplained.
- Taxpayers can request a fresh hearing if they explain their situation and provide proof.
- Keeping contact details updated and cooperating with authorities is crucial.
Frequently Asked Questions
Q: What is Section 80TTB?
A: Section 80TTB allows senior citizens to claim a deduction of up to ₹50,000 on interest income earned from bank deposits.
Q: What happens if a taxpayer does not respond to tax notices?
A: The tax department may complete the assessment without the taxpayer’s input, adding unexplained investments to taxable income, which can lead to higher tax demands.
Q: Can a taxpayer living abroad get a fresh hearing if they miss notices?
A: Yes, if the taxpayer explains the reasons for non-response, updates contact details, and cooperates, the ITAT may allow a fresh hearing.
This case highlights the importance of timely communication with tax authorities and the rights of taxpayers to fair hearings, especially for senior citizens and non-residents.